Easy Payment Processing Basics for Growing Businesses
Easy payment processing starts with merchant accounts that connect businesses directly to card networks and banks, allowing funds from customer purchases to move quickly into operating accounts while fees get deducted at the point of authorization. Data from industry reports shows these accounts handle everything from simple credit card swipes to digital wallet approvals, and the process relies on standardized protocols that verify funds availability in seconds rather than days.
How Core Authorization Works in Practice
Authorization begins when a customer presents a card or enters details online, triggering a request that travels through processors to the issuing bank for approval or decline, and this chain uses encryption standards set by payment card industry guidelines to protect cardholder data throughout the exchange. Observers note that settlement follows authorization, typically within one to three business days, when actual funds transfer occurs and the merchant receives net proceeds after interchange fees and processor charges apply, according to transaction logs maintained by networks like Visa and Mastercard.
Those who manage high-volume operations often discover that batch processing at end of day reduces per-transaction overhead compared with real-time settlements, while automated reconciliation tools match sales records against bank deposits to flag discrepancies early. Research indicates that businesses using integrated reporting features cut manual review time by measurable percentages, and this efficiency becomes especially relevant as transaction volumes climb heading into August 2026.
Security Standards and Compliance Requirements
Payment card industry data security standards require encryption, access controls, and regular audits, and merchants who maintain compliance avoid penalties while reducing breach risks that could otherwise lead to costly remediation. Figures from regulatory filings reveal that tokenization replaces actual card numbers with unique identifiers during storage, limiting exposure if systems face unauthorized access attempts.
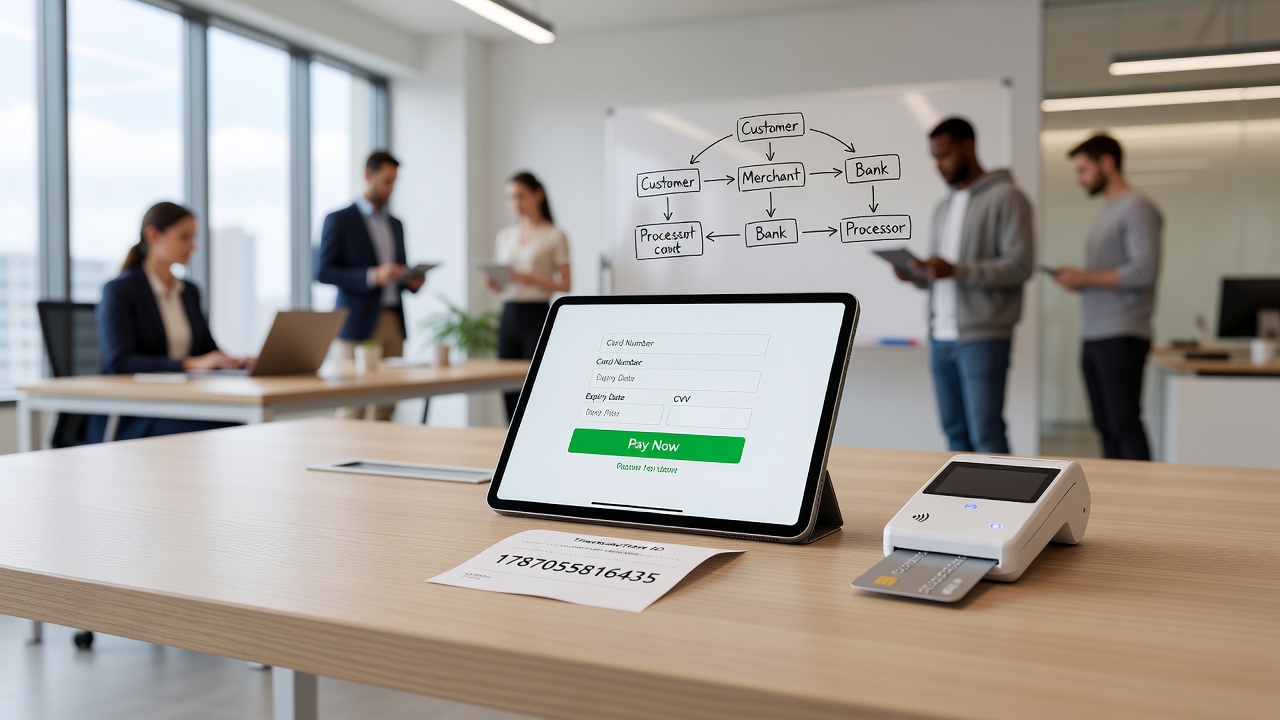
Experts have observed that multi-factor authentication at login points adds another layer without slowing customer checkout flows, and this approach aligns with guidelines from bodies such as the European Central Bank that emphasize consumer protection across borders. In regions outside Europe, similar frameworks from the Federal Trade Commission outline obligations for safeguarding transaction information.
Setup Steps for New Merchant Accounts
Account applications typically request business documentation, bank references, and projected volume estimates, after which underwriters assess risk profiles before approving processing limits. People who complete these steps with complete paperwork often see accounts activated within days rather than weeks, allowing sales to begin without extended delays.
Hardware choices range from countertop terminals to mobile readers that connect via Bluetooth, and software options include virtual terminals for phone orders alongside full e-commerce plugins. Data shows that selecting processors with transparent fee schedules prevents surprise charges that can erode margins over time, and many providers now offer dashboards that track daily, weekly, and monthly activity in real time.
Global Variations and Cross-Border Handling
Currency conversion fees and local regulations affect international sales, yet processors that support multi-currency settlement reduce the need for separate accounts in each market. Researchers discovered that emerging markets in Asia and Latin America have seen increased adoption of contactless methods, driven by infrastructure improvements that support faster authorizations even in areas with intermittent connectivity.
August 2026 projections from payments analysts point to continued growth in these regions, where simplified onboarding tools help smaller operators enter the system without heavy technical overhead. Compliance with anti-money laundering rules remains mandatory everywhere, requiring identity verification that adds initial steps but protects the broader network from illicit activity.
Conclusion
Easy payment processing ultimately rests on reliable connections between merchants, processors, and financial institutions that move money securely while controlling costs through clear fee structures and efficient technology. Businesses that understand authorization flows, maintain compliance, and choose compatible tools position themselves to handle transactions smoothly across channels. Ongoing developments in encryption and reporting continue to shape how these systems operate, providing measurable benefits for operations that track performance against industry benchmarks.